Cryptocurrency Tax in Pakistan: Legal Issues, Reporting and Compliance
Cryptocurrency taxation in Pakistan has become one of the most confusing questions for investors, traders, businesses and blockchain entrepreneurs.
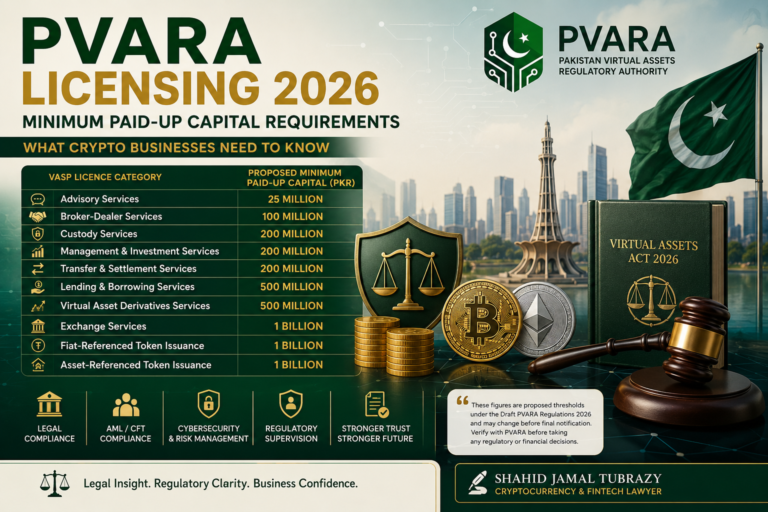
The confusion is understandable. Pakistan has now moved from years of regulatory uncertainty toward a dedicated virtual-asset regulatory framework. The Virtual Assets Act, 2026 established the Pakistan Virtual Assets Regulatory Authority (PVARA), and PVARA’s regulatory framework now includes licensing and compliance requirements for virtual-asset service providers.
But there is an important distinction that taxpayers should understand:
Regulation of crypto businesses is not the same thing as taxation of crypto profits.
As of the current 2026 framework, Pakistan has a dedicated virtual-asset regulatory law, but taxpayers should not assume that the Virtual Assets Act itself creates a specific cryptocurrency tax rate.
Is there a specific crypto tax rate in Pakistan?
This is probably the first question I receive when discussing cryptocurrency taxation.
There has been considerable discussion online about a 15% crypto tax, as well as other proposed rates. However, taxpayers should be careful about treating a number circulated online as an enacted tax rule.
The Federal Board of Revenue currently publishes the Income Tax Ordinance, 2001 amended up to 30 June 2026, while its Finance Act section lists the Finance Act 2026.
The important legal point is that a tax rate should be established from the applicable legislation and official tax rules—not from a social-media post, exchange article, YouTube video or cryptocurrency blog.
Therefore, anyone advising a Pakistani crypto investor to simply pay a fixed “15% crypto tax” should first identify the exact statutory provision creating that liability.
That is particularly important because proposals discussed during the 2026 budget process should not automatically be confused with provisions that were ultimately enacted. Contemporary legal analysis noted that proposed crypto capital-gains amendments did not become a confirmed crypto-specific regime in the enacted framework.
Does that mean crypto income is tax-free?
No.
This is the other dangerous misunderstanding.
The absence of a clearly defined, stand-alone crypto tax rate does not mean that cryptocurrency profits automatically fall outside Pakistan’s income-tax system.
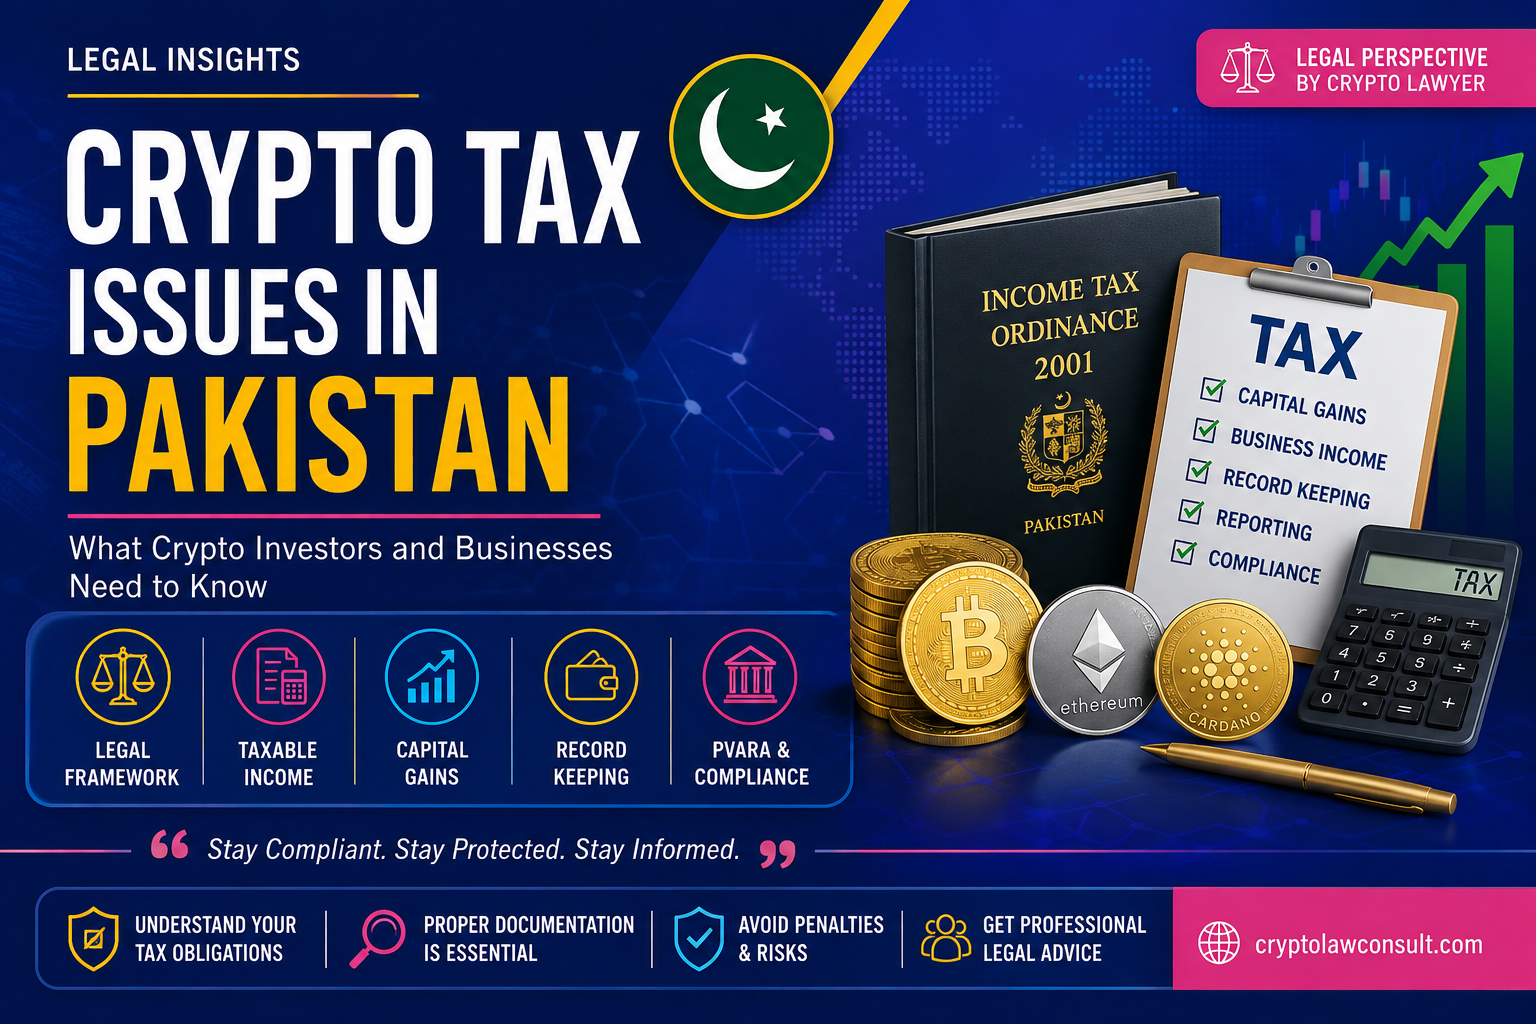
The Income Tax Ordinance, 2001 generally divides taxable income into different heads, including:
- Salary
- Income from property
- Income from business
- Capital gains
- Income from other sources
FBR itself describes these five broad heads of income in its tax guidance.
Consequently, the correct legal question is often not simply:
“Is crypto taxed?”
The better questions are:
What was the nature of the transaction?
How was the crypto acquired?
Was it held as an investment or traded as a business?
Was the income generated from selling an asset, providing services, mining, staking or another activity?
Was the taxpayer resident in Pakistan?
These questions can materially affect the tax analysis.
Capital gains and cryptocurrency
For a person who acquires cryptocurrency as an investment and later disposes of it at a profit, the capital-gains provisions of the Income Tax Ordinance may become relevant depending on the facts and legal characterization of the asset.
The Ordinance contains a general capital-gains framework concerning gains arising from the disposal of capital assets.
However, crypto taxation presents an additional legal difficulty because the legislation does not provide a comprehensive crypto-specific framework addressing every possible type of digital-asset transaction.
That means a taxpayer should not automatically assume that every crypto transaction has the same tax treatment.
For example, there can be substantial differences between:
- Buying Bitcoin as a long-term investment;
- Frequently buying and selling cryptocurrency;
- Operating a professional trading business;
- Receiving cryptocurrency for professional services;
- Mining cryptocurrency;
- Receiving staking rewards;
- Receiving tokens as compensation;
- Issuing tokens;
- Operating a cryptocurrency exchange;
- Providing custody or brokerage services.
Each situation requires its own analysis.
Crypto trading as a business
A person who trades cryptocurrency regularly and systematically may face a different tax analysis from someone who makes occasional investments.
The frequency and scale of transactions, the intention behind acquisition, the organisation of the activity, the source of funds and the overall circumstances can become relevant when determining whether an activity resembles investment or a business operation.
This is why simply saying:
“My crypto profit is a capital gain.”
may not be sufficient.
A taxpayer should maintain evidence demonstrating the nature of the activity and the basis upon which the income has been reported.
For a professional trader or crypto business, this becomes even more important.
What about P2P cryptocurrency transactions?
Peer-to-peer crypto transactions create another layer of complexity.
A Pakistani taxpayer may purchase USDT or another virtual asset through a P2P platform and later sell it for Pakistani rupees. There may be numerous transactions involving different prices, counterparties and wallets.
The taxpayer should therefore maintain a proper transaction history rather than relying solely on bank statements.
Useful records can include:
- Exchange statements;
- Wallet addresses;
- Transaction hashes;
- Purchase records;
- Sale records;
- P2P transaction records;
- Bank statements;
- Payment confirmations;
- Exchange deposit and withdrawal records;
- Evidence of the original acquisition cost;
- Evidence supporting the source of funds.
Blockchain transactions are generally traceable through transaction hashes and wallet addresses, but the blockchain record by itself may not establish the complete tax history of a taxpayer.
The taxpayer needs to connect the blockchain activity with the underlying economic transaction.
What about crypto received for professional services?
Suppose a Pakistani consultant, lawyer, developer or freelancer receives USDT, Bitcoin or another virtual asset as payment for services.
The legal issue is not necessarily limited to what happens when that cryptocurrency is later converted into rupees.
There can be an income-tax question at the time the service income is earned or received, followed by a separate issue concerning any subsequent gain or loss when the digital asset is disposed of.
The precise treatment depends on the taxpayer’s circumstances and the applicable provisions of the Income Tax Ordinance.
This is one reason crypto accounting should not be reduced to simply calculating the amount of money deposited into a Pakistani bank account.
Foreign exchanges do not eliminate Pakistani tax questions
Another common misconception is:
“I trade through a foreign exchange, so Pakistan cannot tax my crypto income.”
That conclusion does not necessarily follow.
FBR’s rules distinguish between Pakistan-source and foreign-source income, and the source rules depend on the nature of the income and the circumstances involved. Section 101, for example, contains specific rules for determining the geographical source of different types of income.
For a Pakistani tax resident using an offshore exchange, the analysis can therefore involve:
- Tax residency;
- Source of income;
- Nature of the income;
- Foreign-source income;
- Applicable Pakistani tax provisions;
- Foreign tax considerations;
- Documentation of transactions;
- Cross-border movement of funds.
A foreign exchange account does not, by itself, answer these questions.
Crypto and wealth statements
Another important issue is the relationship between cryptocurrency holdings and a taxpayer’s overall wealth position.
A taxpayer may have accumulated substantial cryptocurrency over several years but only convert a portion into Pakistani rupees during the relevant tax year.
That does not mean the underlying asset can simply be ignored when considering the taxpayer’s broader tax and wealth-disclosure position.
This is an area where documentation becomes extremely important.
Recent FBR enforcement activity also demonstrates the importance the tax authority places on the accuracy of wealth statements and the source of declared assets. On September 30, 2026, FBR announced action involving allegedly unexplained assets and manipulated wealth statements, including criminal proceedings in one case.
That announcement was not specifically a cryptocurrency case, but it is a useful reminder that taxpayers should maintain a credible documentary trail for the origin and movement of their assets.
PVARA regulation does not replace FBR taxation
The creation of PVARA is a major development for Pakistan’s virtual-asset sector.
PVARA is responsible for licensing and supervising virtual-asset service providers. Its current framework covers areas such as governance, market conduct, technology, AML/CFT/CPF obligations and client-asset protection.
But PVARA regulation and income taxation remain separate legal questions.
A company obtaining a PVARA licence should not assume that the licence itself determines its income-tax treatment.
Similarly, an individual holding cryptocurrency should not assume that the existence of PVARA means that all crypto taxation questions have now been resolved.
The Virtual Assets Act contains tax-compliance provisions for licensed VASPs, requiring them to comply with applicable tax obligations under the Income Tax Ordinance and relevant FBR rules.
This reinforces the need to treat PVARA compliance and FBR compliance as connected but distinct obligations.
What should Pakistani crypto investors do now?
In my view as a cryptocurrency and blockchain lawyer, the safest approach is not to wait until an FBR inquiry, audit or banking question arises.
A crypto taxpayer should maintain a complete transaction file.
At a minimum, I recommend retaining:
- The date and time of each transaction;
- The asset involved;
- Quantity of cryptocurrency;
- Acquisition price;
- Disposal price;
- Transaction fees;
- Exchange records;
- Wallet addresses;
- Transaction hashes;
- Bank/payment records;
- Source-of-funds documentation; and
- Records explaining significant transfers.
For individuals with substantial holdings or complicated trading histories, a professional tax and legal review can help determine the appropriate treatment before filing.
The biggest crypto-tax mistake
The biggest mistake is not necessarily failing to pay a particular percentage.
It is assuming that a percentage found online is automatically the law.
Pakistan’s virtual-asset regulatory framework is developing rapidly. PVARA’s official regulatory framework now includes the Virtual Assets Act and regulations notified in August 2026.
Tax policy, however, must be read separately through the Income Tax Ordinance, Finance Acts, applicable rules, notifications and official FBR guidance.
Crypto investors should therefore distinguish between:
law that has been enacted,
proposals that were discussed,
regulatory guidance,
and
commentary published by third parties.
That distinction is particularly important in a rapidly developing area such as cryptocurrency.
Conclusion
Pakistan’s crypto market is entering a more formal regulatory phase. PVARA now provides a dedicated framework for virtual-asset service providers, while the tax treatment of cryptocurrency still requires careful application of the existing income-tax framework and close attention to future legislative or FBR developments.
For Pakistani crypto investors, traders, entrepreneurs and blockchain companies, the practical message is simple:
Do not ignore tax merely because cryptocurrency taxation is not yet presented in one simple crypto-tax statute.
At the same time, do not assume that a flat 15% crypto tax—or any other percentage circulated online—is automatically applicable without identifying the legal provision supporting it.
Crypto taxation should be analysed transaction by transaction, with proper consideration of the taxpayer’s residency, the nature of the activity, the source and character of income, applicable tax provisions, documentation and the developing PVARA framework.
This article is for general legal and educational information only and does not constitute tax, legal or financial advice. Cryptocurrency taxation can depend on individual facts and may change as Pakistani legislation, FBR guidance and virtual-asset regulations develop. Taxpayers should obtain independent professional advice before filing a return or making a material tax position.
Disclaimer
The information provided in this article is intended for general informational purposes only and should not be construed as legal or financial advice. Readers are encouraged to seek independent professional counsel tailored to their specific circumstances.
Author & Crypto Consultant
Shahid Jamal Tubrazy – Crypto & Fintech Law Consultant
Shahid Jamal Tubrazy is a recognized professional in the field of cryptocurrency and blockchain law, with specialized certification in Crypto Law from Duke University. As an experienced fintech lawyer, he provides comprehensive legal services across the digital asset ecosystem, including regulatory licensing, legal structuring for ICOs, STOs, DeFi projects, and DAOs.
He also offers expertise in crypto dispute resolution, mediation, negotiation, and mergers & acquisitions within the blockchain sector. With a strong portfolio of published work on blockchain regulation and cryptocurrency law, Shahid delivers practical legal insights to help clients navigate complex regulatory landscapes, ensure compliance, and achieve strategic growth in the evolving fintech industry.
📧 Email: cryptolawyer@cryptolawconsult.com
🌐 Website: https://cryptolawconsult.com/
🔗 LinkedIn: https://www.linkedin.com/in/shahidtubrazy/